
Trends in international ocean logistics seem even more confusing than usual lately: more Iranian attacks but more Hormuz traffic; more crude exports but oil prices still around $100 per barrel; more risk of Houthi attacks on passing ships, but more container vessels returning to the Red Sea anyway.
Iran has stepped up the frequency of attacks on vessels around the Strait of Hormuz, partially because transits and crude flows through the waterway have increased in recent weeks. Last week an Iranian projectile sunk a Dubai-linked container vessel, indicating that even some container ships are taking the risk of transiting the strait, though most traffic still comprises tankers.
Despite some estimates that the increase in tankers exiting the Persian Gulf is contributing to Middle East crude exports approaching pre-war levels, crude prices – still pricing in elevated risk – remain high.
Houthi-Saudi violence is intensifying, with recent Houthi advances along the Red Sea increasing its potential leverage over maritime traffic through the Bab el-Mandeb Strait and the likelihood of attacks on passing vessels.
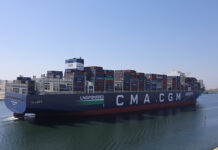
Despite that heightened risk – which since late 2023 had been enough to divert the vast majority of container traffic away from the Red Sea – container carriers continue their steady march back through the Suez, with estimates that transits will fully recover during Q1 of the coming year.
Why carriers are more comfortable going back now than during similar, earlier high-risk stretches is a good question. The answer is probably a mix of high current fuel costs and congestion levels with evolving geopolitical considerations. These considerations may include, as Peter Tirschwell recently pointed out, Houthi interest in security and stability for most Red Sea traffic that could somewhat legitimize the group in relation to the West – alongside increased pressure directed at Saudi Arabia and its passing vessels.
Whatever the reasons, that the Red Sea container rebound is happening gradually instead of all at once should mitigate the extent of schedule disruptions and vessel bunching that will occur as more vessels arrive earlier than slotted. That this restoration unfolded post the early-July Asia – Europe demand peak, and will continue through the coming low demand months will also mean less disruption to shippers than if the return coincided with peak season.
Current port congestion levels – though backlogs and delays are finally easing at Far East hubs – continues to absorb some container capacity, and will help carriers maintain rate levels even as effective capacity increases from vessels circulating more quickly via the Red Sea. Overall though, the Red Sea return – if geopolitics allow its completion – increases the overcapacity risk for carriers in 2027.
At the moment, even with Red Sea-driven effective capacity increases and slumping demand on Asia – Europe trades, spot rates are recently trending up on these lanes after months of declines.
Asia – N. Europe Freightos Baltic Index rates climbed 6% last week to $3,442/FEU and prices to the Mediterranean increased 3% to $3,927/FEU on recent GRIs aimed at putting pressure on rates as 2027 long term contract negotiations get underway. Some forwarders are skeptical however, that increases will stick given current market conditions.
Transpacific ocean rates were stable but still highly elevated last week at $8,126/FEU to the West Coast, with prices up 1% to $9,700/FEU for the East Coast. Daily rates so far this week are showing signs of increase – despite expectations that volumes are finally cooling – possibly due to capacity reductions as the lanes enter slow season.
Last month some carriers announced plans for significanttransatlantic container price increases in October. So far though transatlantic spot rates have increased only about $200/FEU to $2,850/FEU since the end of September. Prices are however 25% higher than a year ago, possibly reflecting upward pressure from elevated bunker costs.
In air cargo, the EU is set to introduce a November 1st €2 small parcel handling fee on top of the €3 customs surcharge introduced in July for low value imports that previously entered via the de minimis exemption. This additional fee could increase the China – Europe e-commerce volume draw down seen since July, which has led to some downward pressure on air cargo rates and shifted freighter capacity to other lanes.
Freightos Air Index data show ex-China rates increased last week, possibly on a post-Golden Week backlog rebound or signalling the start of peak season pressure. Prices posted a sharp 19% gain to $6.88/kg to the US and an 8% climb to $3.87/kg to Europe.
But while the global benchmark is 30% higher than a year ago on elevated fuel costs and volume growth – with transpacific rates 25% higher year on year – Asia – Europe prices are down 3% compared to last October, possibly reflecting e-commerce volume adjustments on this lane.
Judah Levine, Head of Research, Freightos Group